Committed cost is the money a business is contractually obliged to spend — every purchase order, subcontract order and hire agreement placed — whether or not the invoice has arrived yet.
The invoice may be weeks away; the obligation exists the moment the order goes out. That is what makes committed cost the earliest honest signal a construction job gives you about where its cost is heading.
Committed vs actual vs forecast cost
Three cost figures get confused all the time. They answer different questions:
| Figure | What it is | What it tells you |
|---|---|---|
| Budget | The cost you won the job on | What the job should cost |
| Committed cost | Orders placed, invoiced or not | What you have promised to spend |
| Actual cost | Cost booked: invoices, labour, plant | What has already hit the ledger |
| Forecast final cost | Committed + cost still to commit + known risks | What the job will cost |
Two related terms are worth knowing:
- Open (or outstanding) commitment is committed cost minus what has been invoiced against those orders — the bills still to come.
- Uncommitted budget is the budget for lines you have not yet ordered. The forecast assumes that work is still bought at budget unless you know otherwise.
So a simple forecast is: forecast final cost = committed cost + uncommitted budget + known risks and variations not yet ordered. Actual cost does not appear in that sum at all — once an order exists, the invoice is only a matter of timing.
A worked example
The figures below are illustrative: a £120,000 ceilings package on a fit-out job, six weeks in.
| Order | Committed | Invoiced so far |
|---|---|---|
| Subcontract order — installer | £84,000 | £30,000 |
| Purchase order — grid and tiles | £31,500 | £11,300 |
| Purchase order — access hire | £4,200 | £0 |
| Total | £119,700 | £41,300 |
On these numbers the package is £300 inside budget, and the ledger shows only £41,300 spent — barely a third of the budget. Everything looks comfortable.
Then the client asks for an extra bulkhead detail on two floors, and you instruct the installer: a £6,800 addition to the subcontract order. Committed cost is now £126,500 — £6,500 over budget, today — while actual cost hasn't moved a penny. If the client variation that pays for the bulkheads hasn't been priced and agreed, that £6,500 is margin gone. If you only watch actuals, you won't see it until the installer's invoices land, typically four to six weeks later — which is usually exactly the window in which you could have recovered it.
How orders create commitments
Committed cost is only as good as the orders behind it. On a well-run job:
- Every purchase order to a supplier or hire firm is raised against the estimate lines it covers, so committed-versus-budget can be read line by line.
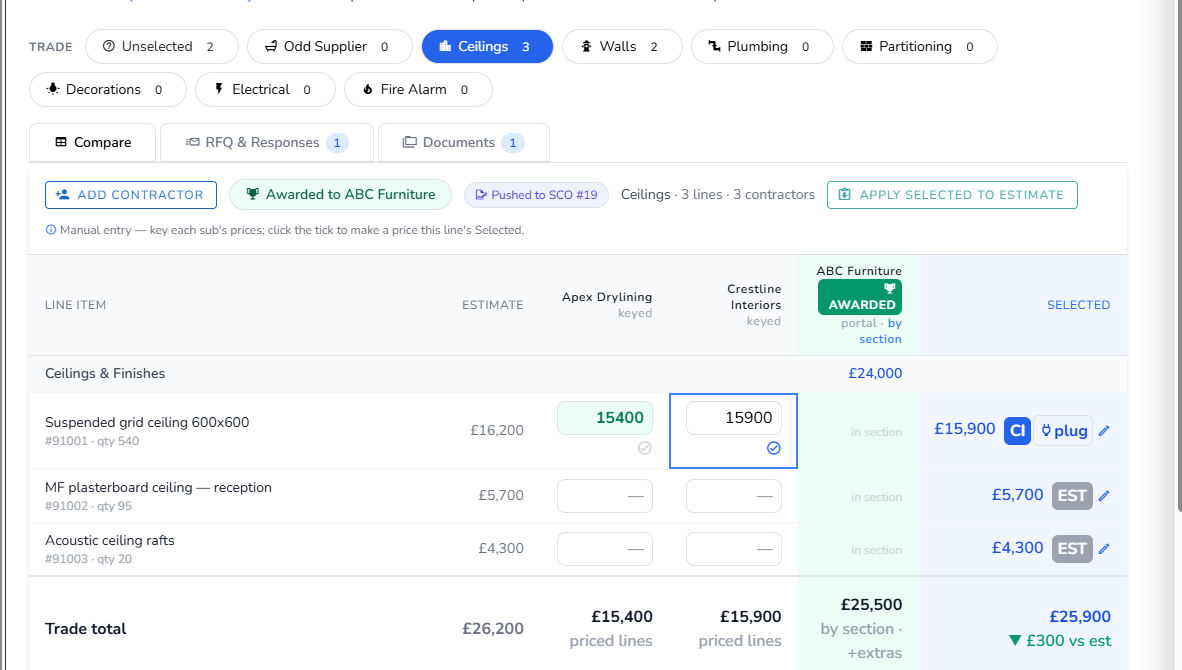
- Every subcontract order carries the tendered price for its package. Awarding a package from a properly levelled tender — see comparing subcontractor prices line by line — means the commitment matches what you actually bought.
- Changes to an order — a variation instructed to a subcontractor, an extra delivery — increase the commitment when they are instructed, not when they are invoiced. See what is a variation in construction.
- Approval sits before commitment. An order that has to be signed off before it is issued can't commit cost nobody saw. The trick is setting sign-off by value so it protects margin without stalling the site — see PO sign-off without the bottleneck.
Why committed cost matters
Actual cost tells you about the past; committed cost tells you about the near future. Contractors who reconcile only against actuals are always several weeks behind the truth. Committed cost is also what makes a cost value reconciliation look forward: comparing committed against budget, package by package, shows erosion while the package can still be renegotiated, value-engineered or recovered through a variation.
How it goes wrong
Committed cost fails when orders don't create commitments visibly:
- POs placed by phone or email and "papered later".
- Orders sitting in a drawer awaiting proper processing.
- Subcontract instructions given on site with no change to the order.
- Orders raised without reference to the budget lines they cover, so nobody can say which package they belong to.
Each gap means the committed figure understates reality, and every report built on it inherits the blind spot.
Committed cost in Vyntworks
In Vyntworks, every purchase and subcontract order is raised from the job's estimate lines and tracked committed-versus-estimated per line, with apportionment across grouped and lump-sum lines handled for you. No order is issued until the right person signs it off, routed by the value at risk. Subcontractor variations are raised against the order they change.
On the cost control side, live CVR reads Budget, Committed, Actual and Forecast Final side by side for every project, and the overspend report lists every line where order spend has passed budget. Live CVR and the overspend report are part of the Vyntworks Intelligence add-on.
US readers: committed cost sits at the heart of job costing, where it is often just called "commitments".
If your committed cost lives in a drawer of POs nobody reconciles, book a walkthrough and we'll show it moving against budget on a job shaped like yours.